Stock Market
Live WireRetiring at 45? Why the 4% rule may not work for your mutual fund corpus and what early retirees can do
This is worth watching because it affects how founders, investors, and operators read the next business cycle.
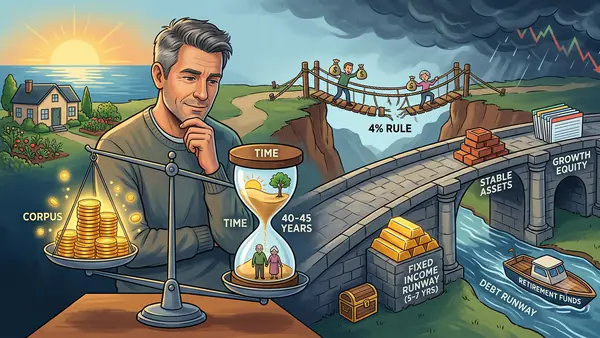
For early retirees, protecting the corpus from a bad start to retirement can be just as important as maximising returns during the accumulation years. (AI-generated image used for representational purpose)AI Quick ReadRetiring early is only half the financial challenge. The bigger question is how to make your retirement corpus last for the next 40 years or more without being forced to sell equity investments when markets are falling.
For someone retiring in their 40s or early 50s, conventional retirement rules may not be enough. The popular 4% withdrawal rule, for instance, was developed using US market data and around a 30-year retirement period. An early retiree in India could need to fund a significantly longer retirement while also dealing with inflation, taxes and rising healthcare costs.
“The 4% rule comes from William Bengen's 1994 work on US market data, calibrated to a 30-year retirement on a balanced US stock and bond portfolio,” said Sandeep Jethwani, co-founder, Dezerv.
Someone retiring at 45 could potentially need to fund 40–45 years of expenses, he said. That makes the withdrawal rate and the way the portfolio is structured particularly important.
The 4% rule is often used as a simple reference for estimating how much a retiree can withdraw from a portfolio in the first year of retirement, with subsequent withdrawals adjusted for inflation.
But early retirees face a much longer withdrawal period.
Sanjiv Bajaj, joint chairman and managing director, BajajCapital Ltd, said a more conservative starting withdrawal rate of around 3–3.5% could be considered as a broad reference point for someone retiring early.
However, neither 4% nor 3–3.5% should be treated as a universal formula.
“The right withdrawal rate depends on the person’s expenses, investment portfolio, inflation assumptions, healthcare needs and legacy goals,” Bajaj said.
Jethwani also cautioned against assigning a single withdrawal rate to every retiree. The required corpus depends on how large the portfolio is relative to expenses and how those expenses evolve during retirement.
Inflation is particularly important. Jethwani said affluent households can experience spending inflation and lifestyle enhancement that are higher than the standard consumer inflation basket.
This means an early retiree should calculate the corpus based on the lifestyle they actually expect to maintain rather than simply applying a generic withdrawal formula.
One of the biggest risks after early retirement is having to sell equity mutual funds during a market correction to meet regular expenses.
Suppose an investor retires at 45 and the stock market falls sharply in the first few years. If the investor has no other source of income and continues withdrawing from equity, they may have to sell more units when prices are depressed. This leaves less money invested for a potential recovery.
This is known as sequence-of-returns risk. It becomes particularly important when the retirement period is long.
Sourced from KnowledgeLoop