Stock Market
Live WireIndia's ₹100 household savings puzzle: ₹33 goes to banks, while ₹39 flows to pension funds and markets
This is worth watching because it affects how founders, investors, and operators read the next business cycle.
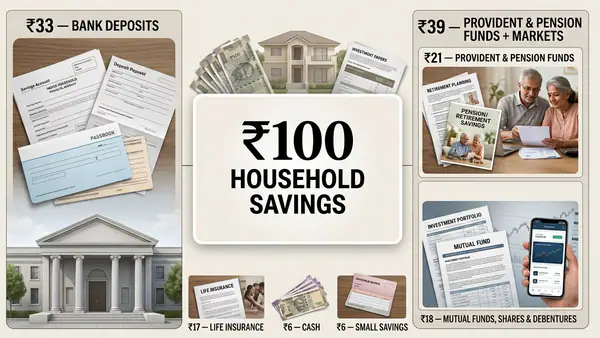
India's ₹100 household savings puzzle: ₹33 goes to banks, while ₹39 flows to pension funds and markets. (AI-generated image)AI Quick ReadIndia’s savings story has changed sharply over the past decade. While bank deposits remain the largest single destination, retirement-oriented and market-linked products together now account for a bigger share of household financial savings.
According to Franklin Templeton India Mutual Fund’s report titled “Financialization of Savings in India – From Safety to Scale”, India’s financialisation journey is improving but remains in its early stages.
Bank deposits accounted for 52% of gross financial savings during FY71-80 (1971-72 to 1979-80). By FY25, their share had fallen to 33%.
Meanwhile, mutual funds, shares and debentures rose from 0% to 18%. Their share increased from 4% in FY21 to 11% in FY24 and 18% in FY25. In FY25, this market-linked category also overtook life insurance at 17%.
Provident and pension funds remained relatively stable, with their share rising from 19% in FY71-80 to 21% in FY25.
Together, provident and pension funds, mutual funds, shares and debentures now account for 39% of household financial savings.
This means that out of every ₹100 of household savings, ₹33 goes to bank deposits, while ₹39 goes to provident and pension funds, mutual funds, shares and debentures.
“India’s savings landscape is being redrawn as households rebalance toward higher-return instruments and accept greater market-linked risk,” according to the report.
Yes. About 65% of India’s population is below 35, with a median age of around 28. “Industry expectations suggest gross financial savings could more than triple over the next decade as digital rails lower entry barriers”, the report noted.
Between March 2020 and March 2025, managed investments grew at a CAGR of about 17.5%, compared with 11.7% for bank deposits.
The difference between the two categories narrowed from nearly ₹32 lakh crore to ₹7 lakh crore, reflecting broader household participation across financial instruments.
Yet as of May 2026, deposits still represented 54% of Indian household assets, second only to China’s 55%, while securities accounted for just 12%.
Indian households remain heavily invested in physical assets. In FY25, an estimated 68% of household wealth was in physical assets, including 10-12% in gold and 57-60% in real estate. This share could moderate to 58-64% as financial holdings increase.
Equities have already risen 2.3 times as a share of household assets, from 2.9% in March 2015 to 6.6% in March 2025.
As of June 2026, India’s equity share was just 7% as compared to 26% in the US and 17% in Taiwan. The report noted that “there remains substantial headroom for further growth”.
Sourced from KnowledgeLoop